Condo vs House Canada: Real Costs, Rules & Which You Qualify For
Quick answer: In the condo vs house Canada choice, condos win on purchase price, location, and low maintenance. Houses win on long-term appreciation, space, and control. Before buying a condo, review the reserve fund and status certificate. Before buying a house, budget 1–3% of its value per year for maintenance.
Comparison table (Condo vs House Canada)
| Factor | Condo | House |
|---|---|---|
| Purchase price | Lower | Higher |
| Monthly fees | Condo fees (50% counted by lenders) | None, but you pay all repairs |
| Maintenance | Shared, handled by the corporation | All yours |
| Surprise costs | Special assessments | Roof, furnace, foundation |
| Appreciation | Usually slower | Usually faster (you own land) |
| Control | Bylaws limit renos, rentals, pets | Full control (within city rules) |
| Key document | Status certificate (ON), Form B (BC) | Home inspection report |
| Best for | First-time buyers, downtown living | Families, long-term owners |
What You Own: Condo vs House
Buying a house means owning the structure and the land beneath it; buying a condo means owning the airspace inside your unit plus an undivided share of everything else. Land appreciates and buildings depreciate, so that distinction drives every cost difference below. Condo ownership stops at the interior finishes: hallways, the roof, the parking garage, elevator shafts and the building envelope all belong jointly to every unit owner, managed by an elected board.
Terminology shifts across provincial lines, and using the wrong term marks a buyer as unfamiliar:
- British Columbia calls the entity a strata corporation, the monthly payment strata fees, governed by the Strata Property Act
- Ontario, Alberta, Manitoba and Saskatchewan use condominium corporation and condo fees
- Quebec uses syndicate of co-ownership under the Civil Code of Quebec
- No Canadian province uses “HOA” or “CC&Rs.” Both terms are American, and neither maps onto Canadian condominium law
Houses split three ways that listings flatten into one word: detached homes share no walls, semi-detached share one, and freehold townhouses share two while carrying no monthly fee. Condo townhouses look identical to freehold ones from the street but carry a fee and remain condos in every legal respec
What Each Property Type Costs Right Now
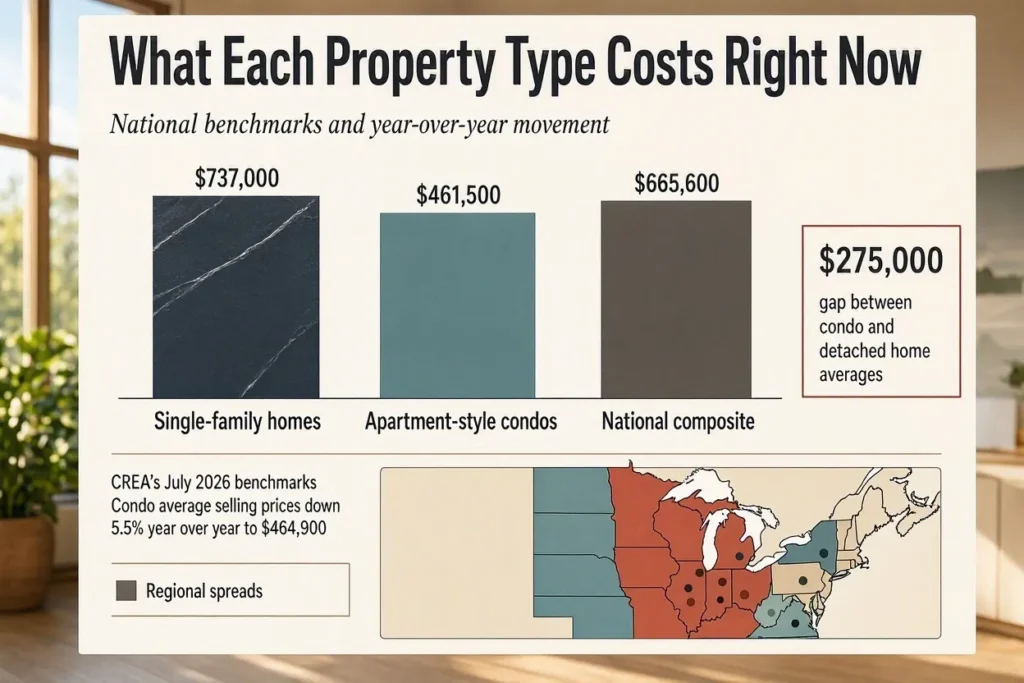
The national gap between a condo and a detached house sits near $275,000, and the gap is widening. CREA’s July 2026 benchmarks put single-family homes at $737,000 against apartment-style condos at $461,500, with the national composite at $665,600. Condo average selling prices fell 5.5% year over year to $464,900 as newly completed units reached a market investors had already left, while detached supply stayed tight. If you’re leaning toward a condo, read our guide to buying a condo in Toronto.
Regional spreads dwarf the national average:
- Metro Vancouver: detached homes averaged $1.98 million in August 2026, up 2.6% year over year, against condo apartments at $759,000, down 6.6%
- Toronto: condo inventory remains heavy with detached pricing largely flat
- Calgary and the Prairies: Alberta prices resumed rising in Q2 2026 after Calgary’s strong 2024 and 2025
CREA forecasts a national average of $686,710 for full-year 2026, a 1.1% increase on 463,336 sales, with Ontario the only province projected to post a sales gain. A falling condo market cuts two ways: entry gets cheaper for buyers holding ten years or more, while anyone reselling within three years carries real downside risk, so the condo vs house decision in Canada tilts toward houses for short horizo See the latest average house price in Canada by property type.
Upfront Costs and Minimum Down Payment
Minimum down payment in Canada is 5% on the first $500,000 and 10% on the portion between $500,000 and $1.5 million. Properties priced at $1.5 million or above require 20% down, since Canada Mortgage and Housing Corporation (CMHC) insurance caps at $1,499,999.
Run the numbers on the national benchmarks:
| Factor | Condo apartment ($461,500) | Detached house ($737,000) |
| Minimum down payment | $23,075 | $48,700 |
| Difference | n/a | $25,625 more |
That $25,625 gap represents years of saving for most first-time buyers. Closing costs widen it further: legal fees, title insurance, a home inspection, and land transfer tax all scale with purchase price. Our guide on how to buy a house in Canada walks through each cost in order.
Land Transfer Tax and First-Time Buyer Rebates
Land transfer tax can swing the condo vs house comparison by more than $15,000, and the swing depends entirely on which province you buy in. Rebate thresholds sit at price points a condo clears and a detached home often does not.
- Ontario: first-time buyers receive a provincial refund up to $4,000, which eliminates land transfer tax entirely on homes under roughly $368,000
- Toronto: a municipal land transfer tax stacks on top of the provincial charge, with a first-time buyer rebate up to $4,475, for a combined maximum of $8,475
- British Columbia: the Property Transfer Tax exemption for first-time buyers applies to homes priced up to $835,000 and phases out between $835,000 and $860,000, worth up to $8,000
- Alberta and Saskatchewan: no land transfer tax, only registration fees on the title and mortgage
- Prince Edward Island: first-time buyers are exempt from the 1% real property transfer tax with no purchase price ceiling
British Columbia shows tax policy deciding a housing type. A Vancouver condo at $759,000 clears the $835,000 first-time buyer threshold and takes the full Property Transfer Tax exemption, worth up to $8,000; a detached home at $1.98 million qualifies for none of it. Three federal programs stack on top regardless of property type: the First Home Savings Account (FHSA) at $8,000 annually to a $40,000 lifetime cap, the RRSP Home Buyers’ Plan (HBP) at $60,000 repaid over 15 years, and the Home Buyers’ Tax Credit (HBTC) at $1,500.
Monthly Carrying Costs Compared
Condo fees are not an extra cost on top of house ownership; they are a prepayment of costs house owners pay unpredictably. Comparing a condo’s total monthly carrying cost against a house’s mortgage payment alone produces a false result every time.Total carrying cost is the only honest comparison unit: mortgage payment, property tax, heat, insurance, condo fees where applicable, and a maintenance reserve for houses.
| Cost category | Condo | House |
| Monthly fees | $300–$1,000+, scaling with square footage and amenities | None, unless in a planned community |
| Property tax | Lower, assessed on the unit only | Higher, assessed on structure and land |
| Insurance | Lower; covers interior and contents, with the corporation insuring the building | Higher; covers the full structure, foundation and roof |
| Utilities | Heat and water often included in the fee | Fully owner-paid |
| Maintenance reserve | Collected monthly into the reserve fund | 1–3% of property value annually, self-funded |
| Irregular costs | Special assessments | Roof, furnace, foundation |
A maintenance reserve of 1–3% on a $737,000 house works out to $7,370 to $22,110 per year, or $614 to $1,842 monthly. Most house buyers never set that money aside, which is why a $12,000 roof replacement or an $8,000 furnace failure feels like a catastrophe rather than a scheduled expense.Condo fees rise. A $400 monthly fee reaching $520 within five years reflects ordinary inflation in cleaning contracts, insurance premiums and utility rates, not mismanagement. No individual owner controls the increase: the board votes, and every unit pays.
Which One Can You Actually Qualify For?
Condo fees reduce your maximum mortgage, because lenders count 50% of the monthly fee as a housing cost inside your qualifying ratios. Federally regulated lenders apply the Office of the Superintendent of Financial Institutions (OSFI) Guideline B-20 stress test to every application, insured or uninsured. Run the numbers to see how much mortgage you can afford in Canada.
The qualifying rate is the higher of your contract rate plus two percentage points, or a 5.25% floor. With five-year fixed rates near 4.24% as of early September 2026, the operative qualifying rate lands around 6.24%. Your lender then tests two ratios at that stressed rate rather than your actual rate:
- Gross Debt Service (GDS): mortgage principal and interest, property tax, heat, and 50% of condo fees, divided by gross income, capped near 39%
- Total Debt Service (TDS): everything in GDS plus car loans, credit card minimums and student loans, capped near 44%
Failing either ratio ends the application, and a $700 monthly condo fee adds $350 to your Gross Debt Service (GDS) calculation, cutting borrowing capacity by roughly $50,000 to $60,000 at current qualifying rates. Condo applications face a second layer houses never encounter, since lenders underwrite the building’s finances alongside yours: litigation, an underfunded reserve, or a high proportion of rented units can trigger a larger required down payment or an outright decline no matter how strong the applicant. Pre-approval covers the borrower, not the building.
The Documents That Decide a Condo Purchase
Every Canadian province requires the condo corporation to disclose its financial condition to a prospective buyer, and the document has a different name in each one. Making an offer conditional on review of that document is the single most protective step in a condo purchase.
| Province | Document | Governing statute | Delivery deadline | Maximum fee |
| Ontario | Status Certificate | Condominium Act, 1998, s. 76 | 10 days | $100 including taxes |
| British Columbia | Form B: Information Certificate | Strata Property Act, s. 59 | 7 days | $35 plus $0.25 per page |
| Alberta | Estoppel Certificate | Condominium Property Act | 10 working days | Varies by document package |
| Manitoba | Disclosure Certificate | Condominium Act (Manitoba) | Statutory | Varies |
| Saskatchewan | Information Statement | Condominium Property Act | Statutory | Varies |
| Nova Scotia | Certificate of Financial Standing | Condominium Act (Nova Scotia) | Statutory | Varies |
Ontario caps the status certificate at $100 including taxes and materials, so buyers paying rush-service premiums are overpaying against a statutory ceiling. Each document binds the corporation legally: an Alberta estoppel certificate prevents the condominium corporation from later imposing an obligation it failed to disclose. British Columbia’s Form B covers the current strata fee, approved or anticipated special levies, the contingency reserve fund balance, outstanding liens on the strata lot, and any active litigation, and since 2023 it has also summarized the strata’s insurance coverage and electrical planning report.
Read for four things specifically:
- Reserve fund balance measured against the building’s projected capital needs, not against a dollar figure that merely sounds large
- Approved or contemplated special levies, which transfer to you on closing
- Litigation, since lawsuits depress resale value and complicate financing
- Rental and pet restrictions, which determine whether your intended use is permitted
How to Read a Reserve Fund Study
A reserve fund study predicts special assessments; the reserve fund balance alone does not. The study is an engineering document projecting the remaining useful life of major building systems and the 30-year replacement cost, so compare the current reserve balance, the projected requirement at each replacement date, and the recommended annual contribution: a building holding $800,000 against a $3 million envelope replacement due in six years is underfunded, and the gap arrives as a fee increase or a special levy.
British Columbia now enforces this through Bill 44, which removed a strata’s ability to opt out of depreciation reports and required current reports in Metro Vancouver, the Fraser Valley Regional District and the Capital Regional District by July 1, 2026, with all other regions by November 1, 2026. Special assessments run from a few thousand dollars to more than $100,000 per unit for full building envelope or structural work, while a house owner facing a $40,000 foundation repair simply receives the bill alone instead of by board vote.
Maintenance, Time and Daily Friction
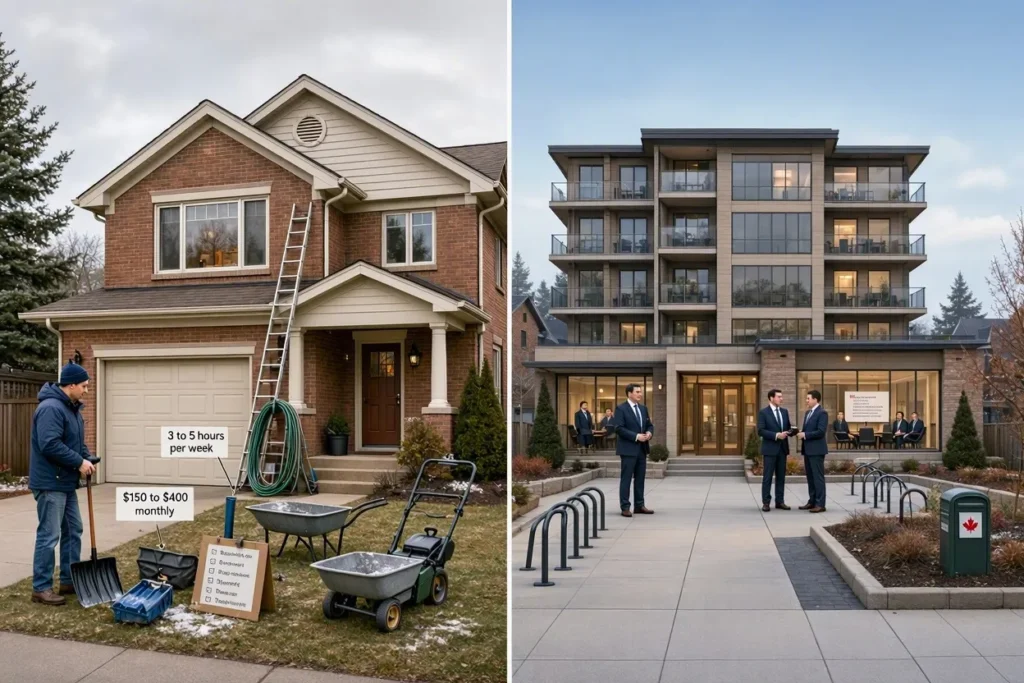
House ownership consumes 3 to 5 hours per week in routine upkeep; condo ownership consumes close to zero. Snow clearing, lawn cutting, gutter cleaning, furnace filter changes, weatherstripping and exterior paint all fall to the house owner, and hiring the work out converts those hours into roughly $150 to $400 monthly for basic lawn and snow service in most Canadian cities.
Condo owners trade that labour for governance. Renovating a kitchen may require board approval, while pet weight limits, short-term rental bans, balcony restrictions and quiet hours sit in the bylaws and bind you from the day you take possession. Anyone planning to list on a short-term rental platform confirms the bylaws permit it before making the offer, not after.
Appreciation, Resale and Rental Restrictions
Houses have appreciated faster than condos across most Canadian markets over the past decade, because land appreciates while buildings depreciate. Land scarcity in established neighbourhoods drives detached values, and a condo unit includes almost no land. The pattern isn’t universal: a condo in a transit-connected downtown core can outperform a detached home in a declining suburb, since location beats property type in any individual comparison.
Resale liquidity differs in a way sellers discover late. Condo buildings hold dozens of near-identical units, so a seller competing against eleven others in the same building competes primarily on price, while detached homes are differentiated by lot, layout and finish, which supports pricing power in slow markets. Rental restrictions then cut against condo investors specifically, since many corporations cap the number of units that may be rented, require board approval of tenants, or prohibit short-term rentals outright. Houses carry no equivalent restriction, and a house with a legal secondary suite generates two income streams where a condo generates one.
Buying From Outside Canada
Non-residents purchasing Canadian property face taxes and financing requirements that Canadian residents do not, and both scale with property price. British Columbia and Ontario levy speculation and vacancy taxes on foreign-owned residential property, and several municipalities add vacant home taxes on top.
Non-resident buyers typically face larger minimum down payments than the 5% floor available to residents, and the FHSA, Home Buyers’ Plan and provincial first-time buyer rebates are unavailable without Canadian residency or citizenship. Federal restrictions on residential purchases by non-Canadians have been amended repeatedly since 2023, so verify current rules with a Canadian real estate lawyer before making an offer.
Conclusion
Two questions settle the condo vs house choice faster than any comparison table: how long you’ll hold the property, and what your down payment covers. Condo prices fell 5.5% nationally in the twelve months to July 2026, so a three-year horizon carries real downside while a ten-year horizon absorbs the cycle, and the $25,625 gap between a condo and detached minimum down payment decides the question outright for many first-time buyers. Run the total carrying cost on both options at a qualifying rate near 6.24% rather than the contract rate, then request the status certificate, Form B or estoppel certificate and read the reserve fund study before the conditional period closes. In Ontario, that document costs $100 and takes 10 days.
Frequently Asked Questions
Johnson
Johnson leads real estate content at Civic Homes, covering home buying, selling, mortgages, renting, and market trends across Canada. He researches provincial rules, mortgage regulations, and city-by-city housing data to explain the Canadian market in plain, practical terms. His guides help buyers, sellers, renters, and investors make smarter housing decisions.
Related Posts