How to Invest in Real Estate Canada: 7 Proven Paths
Most people who ask how to invest in real estate Canada picture a rental property and a stack of mortgage paperwork. That’s one path, but it’s not the cheapest or the fastest one anymore. A $500 REIT purchase gets you exposure to thousands of apartment units by lunchtime. A $500,000 rental property gets you a tenant, a mortgage, and a decade-long commitment. Both count as real estate investing. Neither works well without knowing the numbers first.
This guide breaks down seven entry points, from REITs to Mortgage Investment Corporations, and shows what each one actually costs, what it pays, and who it fits.
What Real Estate Investing Means in Canada
Real estate investing in Canada means buying property or property-backed securities to generate rental income, capital appreciation, or both. A primary residence doesn’t count: it builds equity but no cash flow, and the Canada Revenue Agency (CRA) doesn’t tax its sale like an investment property. Buy a duplex, live in one unit, and rent the other, and lenders often treat that under owner-occupied rules rather than investment-property rules, changing the down payment, mortgage rate, and tax reporting compared to a pure rental purchase.
Four groups drive most decisions in this market: individual landlords buying single properties, passive investors buying shares of Real Estate Investment Trusts (REITs), house flippers on short renovation timelines, and accredited investors placing capital into private funds or syndications. Each needs a different amount of capital and time. Investing from abroad? Check whether foreigners can buy property in Canada first.
The 7 Ways to Invest in Real Estate in Canada
Seven paths cover almost every entry point into the Canadian market. Some need six figures and a mortgage broker. Others need $100 and a brokerage account.
| Investment Type | Starting Capital | Time Commitment | Liquidity |
| REITs and ETFs | $100–$500 | Low | High (trades daily) |
| Rental property (residential) | 20% down payment | High | Low (months to sell) |
| House hacking | Existing home equity | Medium | N/A |
| House flipping | High (purchase + renovation reserve) | Very high | Low |
| Commercial real estate | High (purchase + renovation reserve) | Very high | Low |
| Real estate crowdfunding | $150,000–$300,000+ | High | Low |
| Mortgage Investment Corporation (MIC) | Varies by fund | Low | Low to medium |
REITs and ETFs
Real Estate Investment Trusts (REITs) own income-producing property, apartment buildings, warehouses, and retail plazas, and pay out most of their taxable income to shareholders as distributions. Canadian Apartment Properties REIT (CAPREIT) trades on the Toronto Stock Exchange (TSX) and lets an investor buy exposure to thousands of rental units for the price of one share. No tenant calls, no furnace repairs. The trade-off: REIT prices move with the stock market, so the diversification benefit against a stock-heavy portfolio is smaller than owning physical property outright.
Rental Property
Rental properties remain the most common entry point. An investor buys a single-family home, condo, or small multifamily building and collects rent that ideally covers the mortgage, property taxes, insurance, and maintenance, with income left over. Returns in strong Canadian rental markets typically run 7% to 12% annually when both rental income and appreciation are counted. The work is real: screening tenants, budgeting for a 5% to 10% annual vacancy rate, and staying available for emergency repairs at 11 p.m. on a Sunday. If you sell later, know the tenant rights when a landlord sells.
House Hacking
House hacking works for anyone who already owns a home with a basement or extra unit. Convert the basement into a legal suite, rent it to a tenant, and collect $800 to $1,200 a month in many Canadian markets while living in the property yourself. Owner-occupied mortgage rules apply, so the down payment requirement is lower than a pure investment purchase.
House Flipping
House flipping means buying an undervalued property, renovating it, and selling for a profit within a short window. Since January 1, 2023, the CRA taxes profit on a property sold within 12 months as full business income, not as a capital gain. That single rule change removed the tax advantage that made fast flips attractive for a decade, and most serious flippers now plan holds beyond one year unless the deal’s margin can absorb full marginal tax rates.
Commercial Real Estate
Commercial real estate covers office buildings, retail plazas, and industrial space leased to businesses rather than individuals. Leases typically run 5 to 10 years, which produces income more predictable than month-to-month residential tenancies. Entry capital starts around $150,000 to $300,000 for smaller properties, and lenders often require a 25% down payment or more.
Real Estate Crowdfunding
Real estate crowdfunding pools money from multiple investors into a specific development or property, with minimum investments ranging from $500 to $25,000 depending on the platform. Some platforms restrict participation to accredited investors, meaning individuals who meet minimum income or net worth thresholds set by provincial securities regulators.
Mortgage Investment Corporations (MICs)
Mortgage Investment Corporations (MICs) invest in private mortgages rather than physical property. A MIC pools investor capital and lends it to borrowers who don’t qualify for a traditional bank mortgage, often due to self-employment income or a limited credit history. Returns tend to be higher than a savings account, and the underlying asset is a secured loan rather than a building, which changes the risk profile compared to REITs.
How Much Money Do You Need to Start?
The minimum to start investing in Canadian real estate is $100 through a REIT purchase. A rental property purchase needs a minimum 20% down payment on top of closing costs, land transfer tax, and a cash reserve for vacancies.
Here’s what that looks like at different price points. A $500,000 rental property requires a $100,000 down payment plus roughly $10,000 to $15,000 in closing costs, legal fees, and land transfer tax in most provinces. A $300,000 condo needs $60,000 down under the same math. Compare that to a REIT purchase of $500, which buys fractional exposure to an entire portfolio of apartment buildings without a mortgage application.
Alberta charges no provincial land transfer tax at all, a real cost advantage over Ontario or British Columbia, where transfer taxes can add 1% to 2% of the purchase price on top of the down payment.
How to Finance an Investment Property in Canada
Financing an investment property differs from a primary residence in three ways: a higher down payment, a mandatory stress test, and unit-based classification. Lenders require a minimum 20% down payment on non-owner-occupied property, versus as little as 5% for many first-time buyers. Every borrower must pass the mortgage stress test, qualifying at a rate above the actual contract rate as a buffer against future payment shock. Properties under five units use standard residential financing; five or more units move into commercial lending with its own rate structure and underwriting.
Investment properties also carry higher interest rates, since lenders treat rental income as less certain than employment income and typically discount it 50% to 80% when calculating borrowing power. Get pre-approved specifically for an investment purchase, not a general pre-approval, because the numbers shift once a lender sees the property type. A Home Equity Line of Credit (HELOC) on an existing home can fund the down payment on a second property, provided enough equity exists, and the combined debt still clears the stress test.
How to Evaluate a Property Before You Buy
A good investment property clears three numbers: a positive cap rate, a positive cash-on-cash return, and rent that meets or exceeds local comparables.
Cap rate measures potential return without factoring in mortgage financing. Calculate it by dividing annual net operating income by the purchase price. A property generating $30,000 in annual net income on a $500,000 purchase price produces a 6% cap rate. Cash-on-cash return goes further and compares annual pre-tax cash flow to the actual cash invested, which accounts for the mortgage and shows what an investor’s own money is earning. Our cap rate calculator works out a property’s yield in seconds.
Beyond the math, four factors separate a good buy from a bad one: historical vacancy rates in the neighborhood, the condition of major systems like the roof and furnace, comparable rents for similar units nearby, and local tenant laws that could limit rent increases or extend eviction timelines. Skipping a building inspection to save $500 has cost more than one investor a $15,000 roof replacement discovered after closing.
Taxes on Real Estate Investments in Canada
Rental income counts as taxable income in Canada, reported annually on CRA Form T776 and taxed at the investor’s marginal rate. Deductible expenses reduce that bill: mortgage interest (not principal), property taxes, insurance premiums, maintenance costs, and property management fees. Capital Cost Allowance (CCA), the tax term for depreciation, lets an investor deduct a portion of the building’s value each year, though CCA claims get recaptured and taxed on sale.
Selling triggers capital gains tax on the increase in value, and investment properties don’t qualify for the principal residence exemption that shelters a primary home. Only 50% of the gain gets included in taxable income under the current inclusion rate, softening the hit versus ordinary income tax. REIT distributions blend ordinary income, capital gains, and return of capital, each taxed differently, so check with an accountant before assuming a REIT’s yield is the after-tax return you actually keep.
Risks Every Investor Should Plan For
Five risks show up across nearly every Canadian real estate investment: government intervention, interest rate exposure, illiquidity, vacancy, and market downturns.
Housing policy is politically sensitive in Canada, and governments at every level have introduced rent controls, foreign buyer taxes, and cooling measures with little advance notice. Rising interest rates increase carrying costs on any variable-rate or renewing mortgage, and a property that cash-flows positively at a 4% rate can turn negative at 6%. Illiquidity means an investor can’t sell part of a building to raise cash quickly; the entire asset has to sell, and that process commonly takes two to four months even in an active market. Vacancy periods generate zero income while property taxes and insurance keep coming due. Market downturns, driven by economic slowdowns or shifting population trends, can stall appreciation for years at a time. Check rental demand in the best cities to rent in Canada.
One way to soften government intervention risk: REITs focused on commercial tenants face less rent-control exposure than those holding residential units, since most rent-control legislation in Canada targets residential leases specifically.
Real Estate vs. Stocks: Which Builds Wealth Faster?
Neither asset class wins outright, since the better choice depends on the investor’s liquidity needs, tax situation, and appetite for hands-on management.
Stocks and bonds can be held inside a Registered Retirement Savings Plan (RRSP) or Tax-Free Savings Account (TFSA), which shelters growth from tax until withdrawal or permanently, in the case of a TFSA. Physical property doesn’t qualify for either registered account, though REITs do, which gives REIT investors a tax advantage that direct property owners don’t get. If an investor hasn’t maxed out RRSP and TFSA contribution room, that registered space often delivers a better after-tax return than an unregistered rental property purchase.
Direct property ownership offers something stocks can’t replicate: leverage from a bank at rates well below what most investors could borrow to buy a stock portfolio. A 20% down payment controlling a $500,000 asset means gains on the full asset value flow to an investor who only put up $100,000, though losses scale the same way in the other direction.
A Step-by-Step Plan to Get Started
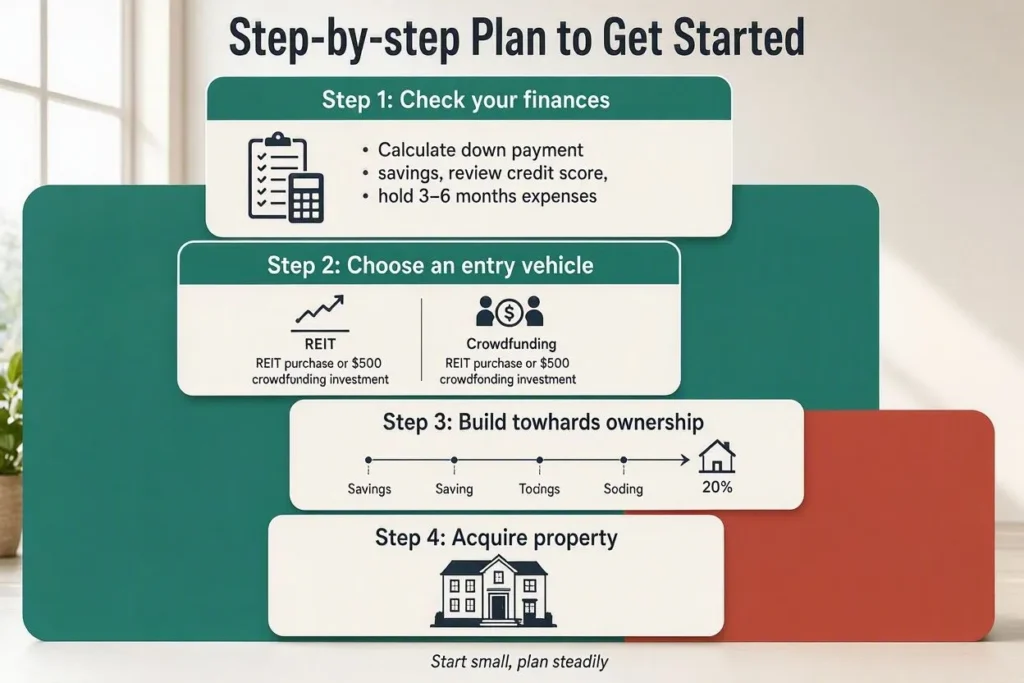
Start with a REIT purchase or a $500 crowdfunding investment if capital is limited, then move toward direct property ownership once savings and credit support a 20% down payment.
Check your finances first. Calculate available down payment savings, review your credit score, and confirm you have three to six months of expenses in reserve before committing capital to any property.
Pick a vehicle that matches your capital and time. A REIT suits an investor with $500 and no interest in property management. A rental property suits an investor with $100,000-plus and time for tenant screening.
Get pre-approved for investment-property financing specifically, not a general mortgage pre-approval, since the numbers differ.
Research target neighborhoods using population growth data, vacancy rates, and planned infrastructure projects as filters.
Run the numbers on every property before making an offer: cap rate, cash-on-cash return, and a comparison against similar rents nearby.
Build a professional team, including a realtor who specializes in investment property, a mortgage broker familiar with rental financing, and an accountant who understands CRA rental rules.
Close, then track income and expenses from day one to simplify the T776 filing at tax time.
An investor who follows this order avoids the most common first-timer mistake: falling in love with a property before confirming the financing and the numbers actually work.
Conclusion
Knowing how to invest in real estate Canada comes down to one rule: match the investment to the money and time you have right now.
A REIT takes ten minutes and about $100. A rental property takes months of saving, a mortgage, and a tenant to manage. Both can build wealth, but only if you run the numbers first: cap rate, cash-on-cash return, financing costs, and what the CRA lets you keep after tax.
Start with the path that fits your bank balance today, not the portfolio you hope to own in five years. You can always move up from there.
FAQs
Johnson
Johnson leads real estate content at Civic Homes, covering home buying, selling, mortgages, renting, and market trends across Canada. He researches provincial rules, mortgage regulations, and city-by-city housing data to explain the Canadian market in plain, practical terms. His guides help buyers, sellers, renters, and investors make smarter housing decisions.
Related Posts